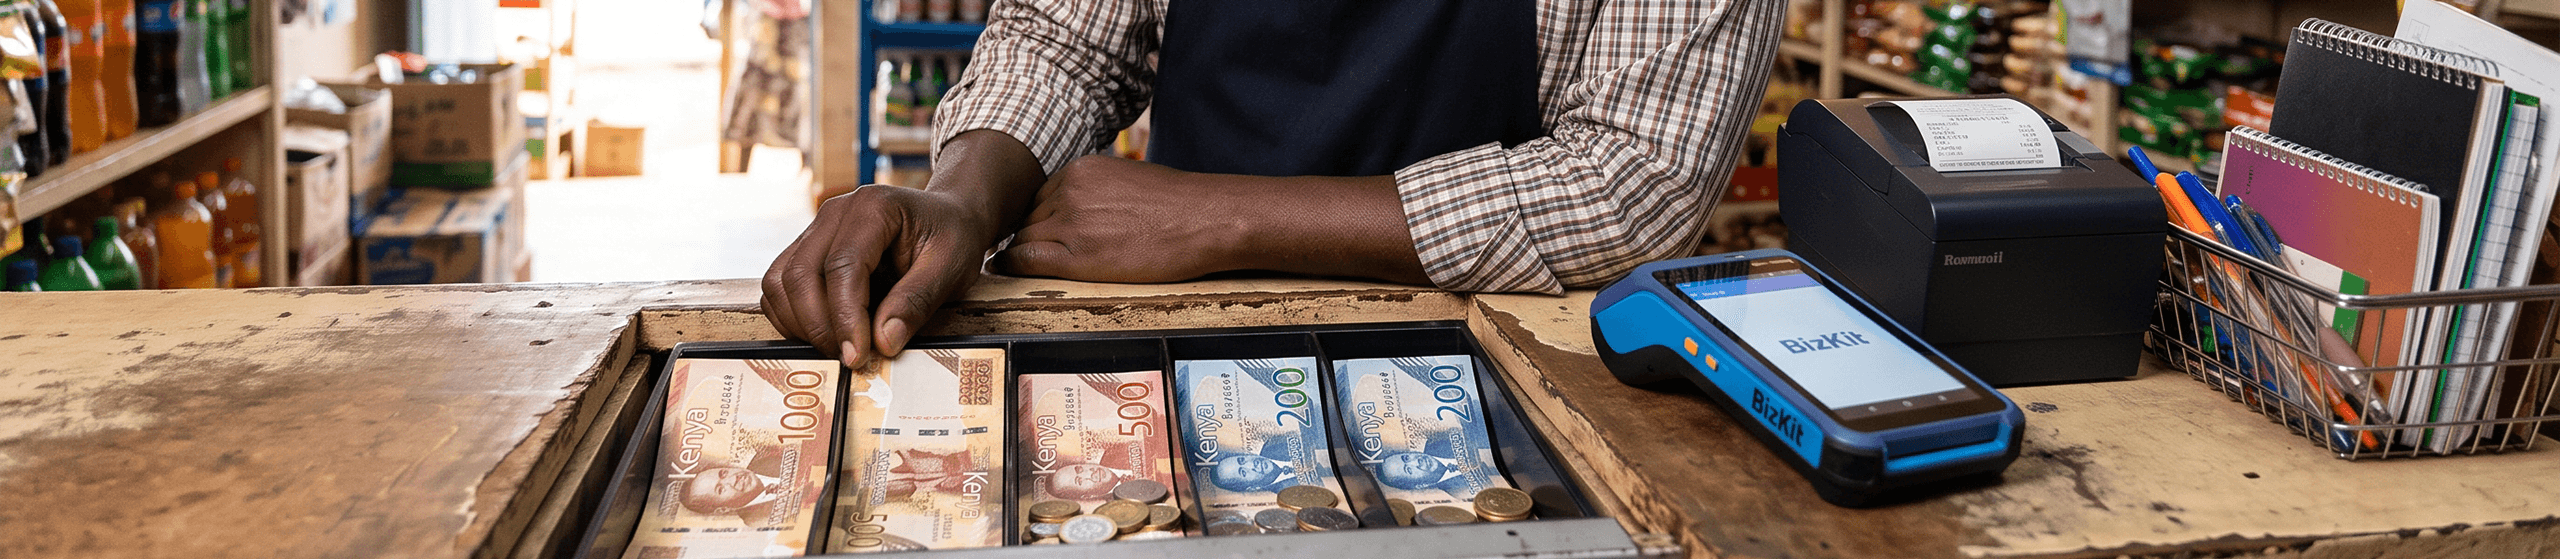
Cash can move through a business many times in a single day, yet small gaps in how it is handled can become significant losses over time. Missing cash, incorrect change, unrecorded sales and poorly documented expenses may each seem minor when they happen once, but repeated transactions can make these problems expensive.
Good cash handling and cash control are therefore not only about keeping money in a secure place. They are about creating a reliable process that makes it possible to know how much cash should be available, where it came from and where it went.
Cash control helps a business identify differences between the money that should be available and the money that is actually available.
Without proper controls, it can be difficult to tell whether a shortage came from an honest mistake, incorrect change, an unrecorded expense, a cancelled transaction or something more serious. The longer these differences go unnoticed, the harder it becomes to identify their source.
The objective is not to make every cash transaction complicated. It is to create enough visibility that unusual differences can be noticed while they are still easy to investigate.
One common weakness in cash handling is treating every movement of money as a sale.
Cash can enter the business through sales, but it can also leave through expenses, supplier payments, staff advances, refunds and other activities. If these movements are not recorded separately, the physical cash balance can become difficult to reconcile with the sales records.
A business therefore needs to distinguish between money generated by selling and money simply moving through the cash drawer. This makes the actual performance of the business much easier to understand.
The most effective approach is to make cash discrepancies visible rather than waiting until the end of the month to discover them. Cash should be counted at defined points, such as when a shift begins and ends. The expected balance can then be compared with the physical cash available. If there is a difference, it should be investigated while the transactions are still fresh.
Small differences should not automatically be ignored. A Ksh 200 shortage may not seem important on its own, but repeated shortages can point to a process problem or create a much larger loss over time.
Cash control becomes more difficult when there is no clear responsibility for the money being handled. If several employees use the same cash drawer without recording who is responsible at different times, it becomes difficult to determine where a discrepancy occurred. This can also create unnecessary suspicion between employees because there is no reliable record to establish what happened.
Where possible, businesses should make responsibility clear for each cash point or shift. This is less about assuming employees are untrustworthy and more about creating accountability that protects everyone.
Cash reconciliation is often treated as simply counting the money and confirming that the numbers match. A more useful approach is to understand why the numbers match or do not match.
The expected cash balance should take into account the opening cash, cash sales, cash refunds, recorded expenses and any other authorised movements. Comparing this figure with the actual cash available can expose discrepancies that would otherwise remain hidden. When there is a difference, the goal should be to investigate the transaction history rather than simply adjusting the records until the figures look correct.
Petty cash and small business expenses can create significant gaps when they are not properly documented.
Money taken from the cash drawer to pay for transport, supplies, delivery costs or other small expenses may feel too insignificant to record individually. Over time, however, these withdrawals can add up and make it difficult to determine where the business’s cash has gone.
Every withdrawal should therefore have a clear reason and supporting record. The amount may be small, but the principle is the same: money leaving the business should be accounted for.
Relying on memory creates unnecessary room for errors. An employee may remember giving change incorrectly but forget which transaction it happened on. A manager may remember taking cash for an expense but not record the amount immediately. At the end of a busy day, several small events can become difficult to reconstruct.
Recording transactions as they happen creates a much stronger trail than trying to rebuild the day’s activities afterwards.
Good controls do not have to mean unnecessary paperwork or complicated procedures.
The best systems fit naturally into the daily workflow. Employees should know what needs to be recorded, when cash should be counted and who is responsible for it. Managers should be able to review differences without manually reconstructing every transaction.
The purpose of control is to reduce uncertainty, not create additional work that employees eventually stop following.
Cash handling becomes easier to control when every movement of money has a clear record and responsibility is clearly defined. Counting cash, recording expenses, reconciling balances and investigating discrepancies can help businesses identify problems before small losses become recurring ones.
The goal is not simply to know how much cash is in the drawer. It is to understand whether the amount makes sense based on everything that happened during the day.
With accurate transaction records, this process becomes much easier. A POS system like BizKit can help businesses keep track of sales, payments, expenses and other cash-related activity, giving business owners better visibility into how money is moving through the business.
How Do You Know Your Business Is Really Under Control?
Cash Handling and Cash Control: How Much Money Is Your Business Really Handling?
Refunds, Returns and Exchanges: Is Your Business Managing Them Properly?
Are Your Discounts Actually Helping Your Business?