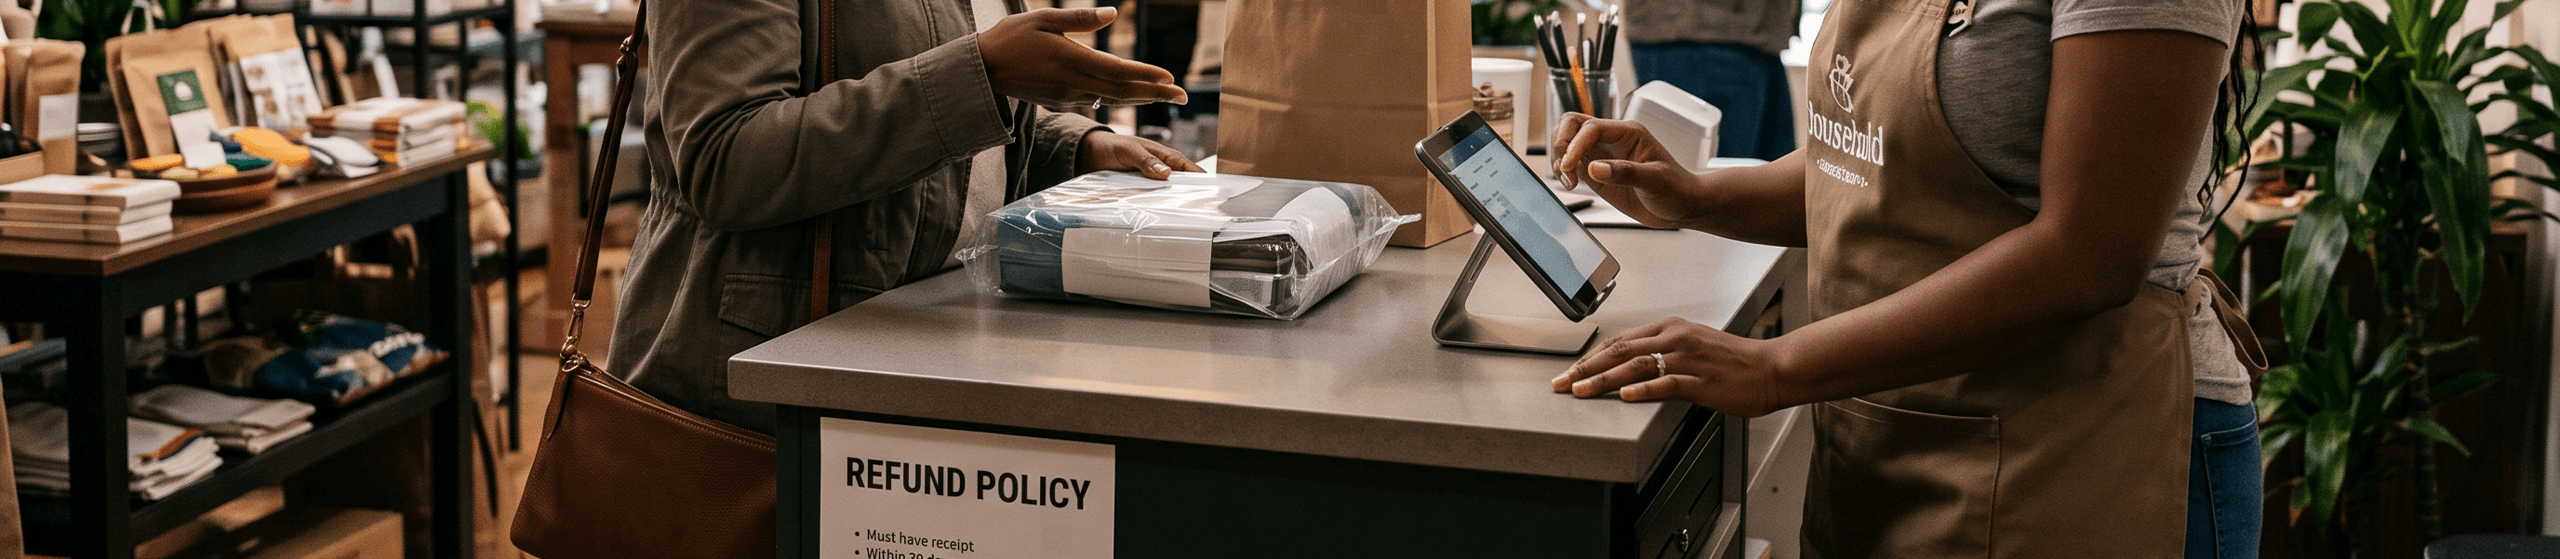
Refunds, returns and exchanges are a normal part of selling. A customer may change their mind, receive the wrong product, discover a defect or realise that what they bought does not meet their needs. While these situations can feel like lost sales, the bigger risk is often how the business handles them.
Poorly managed returns can create stock discrepancies, inaccurate sales records, unnecessary losses and frustrated customers. A clear process helps the business protect its money while giving customers a consistent experience when something goes wrong.
A return happens when a customer brings a purchased product back to the business. A refund is the repayment of the customer’s money, while an exchange involves replacing the returned product with another item.
Although these terms are often used interchangeably, they have different effects on the business. A refund sends money back to the customer, an exchange may create another sale, and a return affects inventory regardless of whether money changes hands.
Treating all three situations in the same way can make it difficult to understand what is actually happening to sales, cash and stock.
A refund should generally be based on a clear policy rather than whatever decision happens to be made at the counter. Businesses need to establish conditions around issues such as defective products, incorrect items, damaged goods and change-of-mind purchases. The conditions may differ depending on the type of product and the circumstances of the return.
The important thing is consistency. If one customer receives a refund for a particular situation while another customer is refused for the same situation, the business can create unnecessary disputes and make it harder for employees to handle future cases.
One of the easiest things to overlook is what happens to a product after it has been returned. A returned item is not automatically equivalent to normal sellable stock. It may need to be inspected, repaired, repackaged, marked as damaged or removed from inventory completely. If the item is simply placed back into stock without being checked, the business may later sell a product that should never have been available for sale.
This is particularly important for businesses handling products that can expire, break, lose value or become difficult to resell once opened.
No. The correct treatment depends on the condition and type of product. A product that is unused and in its original condition may be returned to available inventory. A damaged product may need to be recorded separately. Some items may need to be written off, repaired or returned to the supplier instead.
Separating these outcomes gives the business a more accurate picture of what stock it actually has. Otherwise, inventory records can show products as available even though they cannot realistically be sold.
A useful returns process should make it clear what happens from the moment a customer requests a return until the issue is resolved.
The original transaction should be identified, the reason for the return recorded and the condition of the product checked. The business can then determine whether the item should be refunded, exchanged, returned to stock or treated as damaged. This creates a record of why products are coming back rather than simply adjusting the sale and moving on. Over time, those records can reveal patterns that would otherwise remain invisible.
A high number of returns is not always a customer service problem. It can be a signal that something else in the business needs attention.
If customers repeatedly return the same product because of defects, the supplier may need to be reviewed. If customers frequently receive the wrong item, the picking or sales process may have a problem. If products are regularly returned because customers misunderstood what they were buying, product descriptions or staff communication may need improvement.
The return itself is therefore useful information. Instead of only asking how much money was refunded, businesses should also ask why the product came back in the first place.
A refund does not simply reverse a sale. It can affect revenue, inventory, cash flow and sometimes supplier relationships.
For example, a business may record a refund but fail to correctly adjust its stock. The financial records may appear accurate while the inventory becomes increasingly unreliable. Alternatively, a product may be returned but the business continues treating it as a normal sale in its performance reports. Keeping the financial and inventory sides of the transaction connected helps prevent these gaps.
A return policy should not exist only to protect the business. It should also help customers understand what to expect before they make a purchase. The policy should clearly communicate conditions such as the period within which returns are accepted, the condition products must be in, which products cannot be returned and whether customers receive a refund, exchange or alternative solution.
When these expectations are clear, employees do not have to make up rules during difficult customer conversations, and customers are less likely to feel that decisions are being made arbitrarily.
Refunds, returns and exchanges are not simply transactions that need to be reversed. They are part of the information a business can use to understand its products, customers, inventory and internal processes.
A strong process makes sure that returned products are properly accounted for, refunds are accurately recorded and recurring return patterns are investigated. The goal is not to eliminate every return, but to make sure each one is handled consistently and provides useful information to the business.
Keeping accurate records makes this easier. A POS system like BizKit can help businesses track sales, inventory and customer transactions in one place, making it easier to manage the information behind refunds, returns and exchanges.
Refunds, Returns and Exchanges: Is Your Business Managing Them Properly?
Are Your Discounts Actually Helping Your Business?
Revenue Management: Is Your Business Growing Revenue or Just Chasing Sales?
Pricing and Profitability: What Should Your Business Really Be Charging?